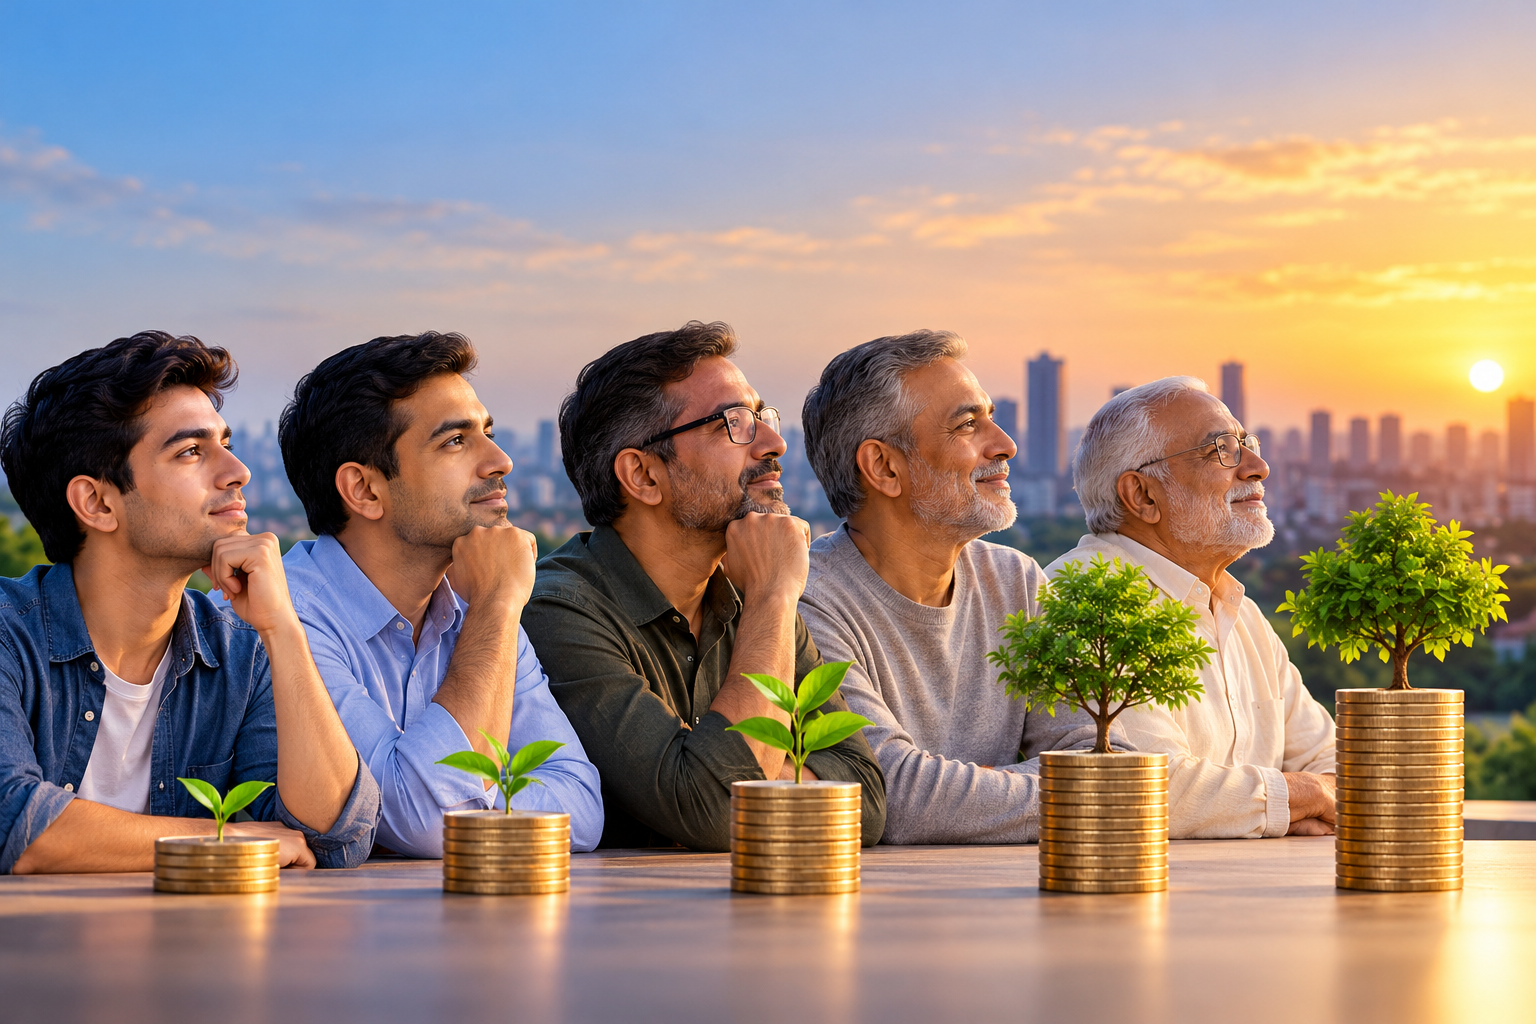
Retirement Planning: How Much Money Do You Need at Age 30, 40, 50 or 60?
Retirement planning: A monthly household expense of ₹50,000 today could rise to nearly ₹3.81 lakh by the time a 30-year-old turns 60, assuming annual inflation of 7%. For people in their 40s and 50s, the challenge is different: they have fewer years to prepare financially before retirement. Understanding how much money you may need at different ages can help you plan your savings more effectively.
Add rightsofemployees.com as a Preferred Source
Retirement may seem like a distant goal when you are in your 30s or 40s. Buying a home, paying off a loan, raising children and managing everyday expenses often take priority. However, postponing retirement planning can make it harder to build a sufficiently large financial cushion.
The main question is not simply how much money you should save. It is whether your savings will be enough to cover your living expenses after your regular salary stops.
For this article, we have considered a person whose current household expenses are ₹50,000 per month, an annual inflation rate of 7%, retirement at age 60 and an expected lifespan of 90 years. The estimates also assume an annual investment return of 8% during retirement.
How much retirement corpus do you need at different ages?
The amount required at retirement depends on how much your present expenses increase over time. Someone who is 30 today has three decades before reaching 60, while a person aged 50 has only 10 years.
Here is an illustrative estimate of the retirement corpus required under these assumptions.
| Current age | Years until retirement | Estimated monthly expenses at 60 | Estimated retirement corpus |
|---|---|---|---|
| 30 years | 30 years | ₹3.81 lakh | ₹11.95 crore |
| 40 years | 20 years | ₹1.93 lakh | ₹6.08 crore |
| 50 years | 10 years | ₹98,358 | ₹3.09 crore |
| 55 years | 5 years | ₹70,128 | ₹2.20 crore |
| 60 years | Retirement begins | ₹50,000 in today’s spending terms | Approximately ₹1.6 crore |
Note: The age-60 figure is a separate illustrative calculation based on ₹50,000 monthly expenses, a 30-year retirement period, 7% annual expense inflation and 8% annual investment returns. All figures are estimates, not guaranteed outcomes. Actual requirements will depend on taxes, investment performance, healthcare expenses, pensions and other sources of income.
These figures represent estimated retirement needs, not the amount a person should already have accumulated at their current age. Existing investments, provident fund savings, pension benefits and other retirement assets can reduce the additional amount that needs to be built.
Retirement planning at 30: Why starting early matters
A person aged 30 has approximately 30 years to prepare for retirement at 60. Although this may seem like plenty of time, inflation can significantly increase the cost of maintaining the same lifestyle.
For example, a household spending ₹50,000 per month today could require around ₹3.81 lakh every month after 30 years if expenses rise by 7% annually.
This does not necessarily mean that a 30-year-old must have ₹11.95 crore saved today. Instead, it highlights the importance of starting early and allowing investments to grow over time.
People in their 30s can focus on building a regular investment habit, increasing contributions as their income grows and avoiding unnecessary withdrawals from long-term investments.
It is also important to balance retirement savings with other financial goals. Building an emergency fund, maintaining adequate insurance and managing expensive debt can help prevent unexpected expenses from disrupting a retirement plan.
Retirement planning at 40: The need to review your progress
By age 40, a person has approximately 20 years remaining before reaching the traditional retirement age of 60.
At this stage, retirement planning becomes more concrete. Household responsibilities may be higher, particularly for people managing home loans, children’s education and other family expenses.
With annual inflation of 7%, current monthly expenses of ₹50,000 could rise to approximately ₹1.93 lakh by age 60.
The estimated retirement corpus under the stated assumptions is ₹6.08 crore.
People in their 40s should review their existing retirement investments rather than focusing only on the final target. The review should include employee provident fund savings, the National Pension System, mutual funds, fixed deposits and other assets specifically intended for retirement.
If the projected investments fall short of the target, increasing monthly contributions, directing part of future salary increases towards investments and reviewing unnecessary expenses may help close the gap.
However, investors should avoid taking excessive risks simply because they feel they have started late. The investment strategy should reflect their financial circumstances, time horizon and ability to withstand market fluctuations.
Retirement planning at 50: Is there enough time left?
For someone aged 50, retirement at 60 is only a decade away. The time available to accumulate savings is shorter, making it important to understand the likely gap between existing investments and the required corpus.
Under the 7% inflation assumption, monthly expenses of ₹50,000 today could increase to approximately ₹98,358 by age 60.
The estimated retirement corpus is ₹3.09 crore under the source article’s assumptions.
At this stage, people should calculate their expected retirement income and compare it with their anticipated expenses. This includes checking provident fund balances, pension entitlements, existing investments and any other dependable sources of income.
It may also be worth reviewing outstanding loans and deciding how they will be managed before retirement. Entering retirement with substantial monthly loan repayments can put additional pressure on savings.
People approaching retirement should also consider how much money needs to remain easily accessible for emergencies. Medical expenses, home repairs and family responsibilities can create unexpected financial demands.
A financial plan should account for these possibilities instead of assuming that all retirement expenses will remain predictable.
Retirement planning at 55: Five years to prepare
At 55, a person planning to retire at 60 has approximately five years remaining to build or strengthen their retirement savings.
The effect of inflation is still significant. Monthly expenses of ₹50,000 today could rise to approximately ₹70,128 by age 60 at an annual inflation rate of 7%.
The estimated retirement corpus under the source article’s assumptions is ₹2.20 crore.
People at this stage should review their retirement plans carefully and avoid relying on overly optimistic investment returns. A sudden market decline shortly before retirement can affect the amount available to generate income.
It is also worth deciding how retirement savings will be divided between investments that provide stability and investments that offer the potential for long-term growth.
Keeping sufficient liquidity is important, but moving all retirement money into low-return investments may create another problem: the possibility that inflation will gradually reduce its purchasing power.
The right balance depends on expected expenses, other sources of income, health considerations and the length of retirement.
Retirement planning at 60: How much money is enough?
Turning 60 does not necessarily mean that a person will stop spending on major financial goals. Retirement may last 25 to 30 years or longer, and the money accumulated over a working lifetime may need to support expenses well into the person’s 80s or 90s.
For someone retiring at 60 with household expenses of ₹50,000 per month, an illustrative calculation suggests that a corpus of around ₹1.6 crore could cover 30 years of expenses if those expenses increase by 7% annually and the investment portfolio earns 8% annually.
This estimate is sensitive to the assumptions used. It does not provide a guarantee that the money will last for 30 years, particularly if investment returns fluctuate, taxes reduce the available income or healthcare expenses rise faster than general inflation.
A retiree who already has a pension or rental income may need a smaller investment corpus than someone who depends entirely on personal savings. Conversely, a person with substantial medical costs, dependants or a higher standard of living may need considerably more.
Retirees should also consider how they will withdraw money from their investments. Taking out too much during the early years of retirement can leave less money available for later years.
A sensible retirement plan should therefore address both the size of the corpus and the strategy for generating income from it.
Why inflation is one of the biggest retirement risks
Inflation can quietly change the financial picture over several decades.
At an annual inflation rate of 7%, expenses rise substantially over time. A household that manages comfortably on ₹50,000 per month today may need several times that amount to maintain a comparable lifestyle in the future.
This is why retirement planning should be based on expected future expenses rather than simply multiplying today’s monthly budget by a fixed number.
Healthcare deserves particular attention. Medical costs, medicines, hospitalization and long-term care may not rise at the same pace as ordinary household expenses. Older people should consider adequate health insurance and a separate financial provision for medical emergencies.
It is also important to review inflation assumptions periodically. Actual inflation may be higher or lower than the rate used in a calculation, changing the amount ultimately required.
How can you build a retirement corpus?
There is no single investment strategy that works for everyone. However, a few basic steps can make retirement planning more effective.
Start investing as early as possible. Beginning early gives investments more time to compound and reduces dependence on large contributions later in life.
Increase investments with income. When salary or business income rises, directing a portion of the increase towards retirement can help investments grow without requiring an abrupt change in lifestyle.
Diversify your investments. Depending on your circumstances, a retirement portfolio may include equity mutual funds, debt investments, provident fund savings and other suitable financial assets. Each has different risks, liquidity characteristics and return expectations.
Review the plan regularly. Retirement targets should be revisited as expenses, income, family responsibilities and market conditions change.
Plan for a longer life. Retirement calculations should not assume that expenses will stop at 75 or 80. Planning for a longer lifespan can reduce the risk of exhausting savings later.
Account for existing retirement benefits. Provident fund balances, pensions, gratuity and other eligible retirement benefits should be included when estimating the additional savings required.
The bottom line
Retirement planning is not about reaching a particular savings figure simply because it sounds substantial. It is about ensuring that your savings and other income sources can support your lifestyle for as long as you need them.
A person in their 30s has more time to build investments, while someone in their 50s may need to review their financial position more urgently. Those already approaching or living in retirement need to focus on preserving purchasing power, managing withdrawals and preparing for unexpected expenses.
The estimates above provide a starting point, but a realistic retirement target should be calculated using your own expenses, current savings, expected retirement age, investment returns and anticipated lifespan.
For a more personalized estimate, investors can use the retirement planning calculator provided by the National Institute of Securities Markets (NISM) to model different assumptions and assess the amount they may need to invest.
Disclaimer: This article is for informational purposes only and should not be considered personalized investment advice. Retirement corpus estimates are based on assumptions and may differ from actual outcomes.
Add rightsofemployees.com as a Preferred Source